Four hands on my investment. Only one worked for me
Before you invest, draw who touches your money, who watches each of them and who you can claim against if it goes wrong. In my case there were four, and only one was on my side.
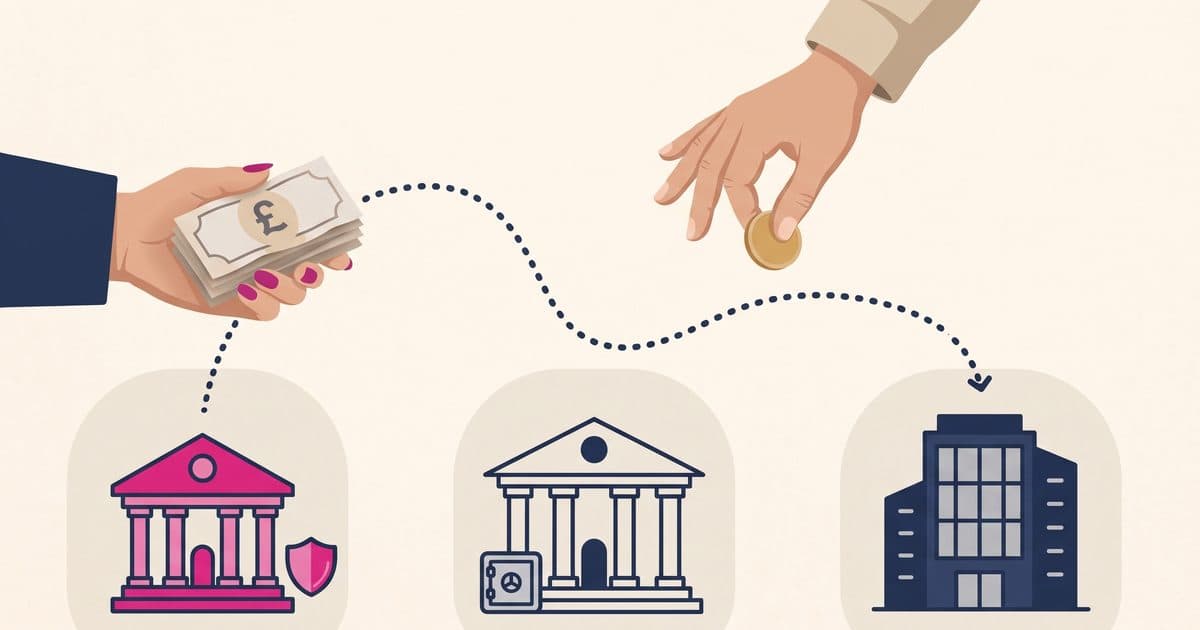
When something breaks in a computer system, the first thing I do is draw it: which pieces there are and who is responsible for each one.
With my investment, I did it too late. The money took this route: it left my company's account, went through a solicitor's client account and from there reached the bank of the company selling the investment. And a fourth hand took a cut without me paying it anything: the deal sourcer who introduced me to the deal.
Only one of those four worked for me. Spoiler: it was the one that gave me my money back.
Three kinds of watchdog
There are three kinds of watchdog. I didn't know that until I was the victim of a fraud:
The regulator. It sets the rules, gives permission to operate and punishes whoever breaks them. It's the referee who can send a player off. But it doesn't give you anything back. And not every activity has one: financial services do (the FCA), and so does legal work (the SRA); a rent-to-rent deal or a deal sourcer's work doesn't.
The Ombudsman or redress scheme. It handles customer complaints, for free, and can make a firm compensate you. Each sector has its own: the Financial Ombudsman for banks and other financial firms, the Legal Ombudsman for lawyers and, in property, two redress schemes, The Property Ombudsman and the Property Redress Scheme.
The compensation scheme. It pays out when a firm authorised by the regulator goes bust or disappears with your money. It works like insurance, with limits.
Hand 1: the company
What they were selling me wasn't a house, it was an investment: money in exchange for a return. Investments are overseen by the FCA, the UK's financial regulator. I asked whether the company was regulated and they told me rent-to-rent contracts didn't need its authorisation. That's true. What it meant, I only understood later: without the FCA, there's no Financial Ombudsman and no FSCS, the compensation scheme, either. Both only cover firms the FCA has authorised. If the company disappears, the most you're left with is the second watchdog in its property version, if the company belongs to one, capped at £25,000. Mine did: I'll tell you about it in the last post.
What to check:
The FCA's public register. If the firm isn't on it, what protection do you have left?
Companies House. Look up each director by name. I only looked at the company's page, saw clean profiles and relaxed. Later I found out that one person can have several profiles, and the other ones were full of dissolved companies. Searching by name takes two minutes.
The accounts. This company's "grew every year". What I didn't stop to think about is that a small company doesn't need an auditor. The accounts are what the company says about itself.
The reviews. The Trustpilot ones were excellent. They tell you how things have gone for someone so far, not what's behind it.
Hand 2: the deal sourcer
A deal sourcer finds property deals for investors. In the UK they have no regulator of their own. They have to be signed up to one of the two property redress schemes, the Property Redress Scheme or The Property Ombudsman, and mine was.
A redress scheme won't give you your investment back, but it was useful to me: more on that in the last post.
I didn't pay her anything, and that felt like an advantage. It wasn't: the company paid her commission as a sales agent, so part of my £31,150 ended up in her pocket. If a middleman is paid by whoever sells the investment, they work for the seller, not for you.
Hand 3: the solicitor
Having a solicitor involved made the whole thing feel legally sound, and she told me in writing that she had seen the leases.
That solicitor wasn't mine. The company had hired her and, even though the contract said she would represent me, I wasn't her client.
The Legal Ombudsman, which handles complaints about lawyers, turned my case down because I wasn't her client. Reporting her to the SRA, her regulator, can get her punished, but it won't get you anything back.
What to check:
That she and her firm are on the SRA register. It's the bare minimum, not a guarantee.
Who she actually represents. It doesn't matter who pays the bill: if there's no client care letter in your name, she isn't your lawyer.
Hire your own solicitor. If the company can't show you the documents "for confidentiality reasons", let yours see them: they're bound by confidentiality too. If they won't show them to your solicitor either, be suspicious.
Hand 4: my bank
The bank was the only hand on my side: my company was its customer. It's regulated by the FCA, it has an Ombudsman and, since October 2024, a rule that requires it to refund victims of certain bank transfer scams. That's how I got my money back: I explain it in the next post.
But there's a catch that left other victims out: the account you pay from has to be in the name of whoever signs the contract. Your company's contract, your company's account. A contract in your name, an account in your name. Mixing them makes claiming harder.
Before you hand over your money
What I wish I'd known, I've turned into a guide of questions: Before you put money into a property deal. In a few minutes you'll see which hands in your investment have someone watching them and which don't.
If they won't show you the documents, I'd be wary.
Where all this comes from
- FCA register: check whether a firm is authorised. Financial Services Register
- SRA: the register of solicitors. Solicitor check
- Payment Systems Regulator: protection for victims of bank transfer scams since 7 October 2024. PSR
Did this article help?